
In the fast-paced world of business, securing the right type of financing is a crucial step for growth and sustainability. As a senior journalist who’s seen the myriad of challenges and opportunities in the business world, it’s clear why business owners often find themselves at a crossroads: choosing between a business credit line and a business loan. Both have their perks and pitfalls, and making the right choice can be the difference between financial triumph and adversity.
Understanding Business Credit Lines and Loans
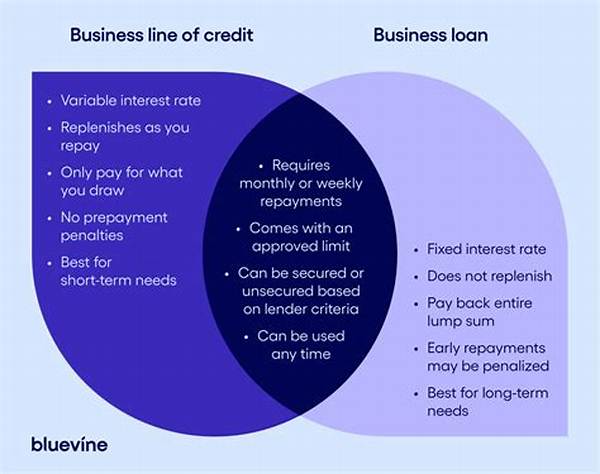
Alright, let’s get down to business—literally. Picture this: you’re sitting in your office, sipping that third cup of coffee of the day, pondering the eternal question: “Business credit line vs business loan: which financing option is right?” Here’s the lowdown. A business credit line is like having a financial safety net. You’ve got a set amount of funds you can dip into when the need arises. Flexibility is the name of the game here. Business loans, on the flip side, are like your mom and dad—solid and reliable. You get a lump sum upfront and repay it over time with interest. So, what’s the vibe? If you’re all about that flexible life, a credit line might just be your jam. But if you need big bucks to make those major moves, a loan could be your best bet.
Pros and Cons in Plain Speak
1. Credit Line Flex: Got expenses popping up now and then? A credit line is your go-to.
2. Loan Lump Sums: Need a heap of cash to kickstart that killer project? Loans are where it’s at.
3. Repayment Chill: Credit lines let you pay as you go—super chill.
4. Rate Differences: Loans usually have fixed rates. Credit lines? They can keep you on your toes.
5. Business credit line vs business loan: which financing option is right? Well, it depends on your flavor of financial style, friend.
Diving Deeper into Financial Choices
Choosing between a business credit line and a business loan isn’t just about numbers; it’s about strategy and style. Think of the business credit line as that flexible friend who’s down for whatever. You only pay interest on what you actually use, so it’s cash flow-friendly. Plus, this pal never nags—use it when you want, and keep things casual. Loans, though, are like planning a wedding—they require commitment. You get the funds, but you’ve got a schedule to follow for repayment. Business credit line vs business loan: which financing option is right? If your business swings with unpredictable rhythms, a credit line may give you that smooth groove. But if predictability is your anthem, then maybe a loan is the melody you need.
Key Considerations Before Making a Decision
1. Urgency and Use: Consider if immediate, multiple cash needs or a one-time hefty investment best fits your situation.
2. Financial Stability: Assess if consistent repayments or flexible borrowing suits your business pattern.
3. Interest Anxiety: Relax with fixed rates of loans, or roll with the variable vibes of credit lines.
4. Credit and Collateral: Do you have assets to secure a loan, or does the casual nature of a credit line appeal more?
5. Growth Goals: Align your financing type with your short-term and long-term business goals.
6. Accessibility: Need funds at the ready, or are you down with waiting for loan approval?
7. Flexibility vs. Commitment: Consider your comfort level with change or if you lean towards steady agreements.
8. Business Health: Is your cash flow robust and able to handle fixed repayments?
9. Spending Control: Credit lines require discipline to avoid over-borrowing.
10. Bottom Line: Ultimately, in the debate of business credit line vs business loan: which financing option is right?—it’s your business story that will decide.
When to Choose a Business Credit Line
If you’re the type who needs a little wiggle room financially, a business credit line could be your go-to guy. Imagine having your cash needs on a leash—you only dip in when required. Say your business rides the cash flow rollercoaster; this option can smoothly adjust to your ups and downs. It’s like having that friend who’s always game for spontaneous plans. And let’s be real, in the hustle of business, sometimes you don’t want to be tied down. Business credit line vs business loan: which financing option is right? For those living in the fast lane, flexibility is the golden ticket.
When to Opt for a Business Loan
Steady as she goes—if this is your business mantra, a loan might be right up your alley. You’re all about that long game, planning each move like a chess master. Business loans give you that hefty sum at once, letting you strategically dive into big projects without worrying about unforeseen needs. The predictability of set repayments can provide peace of mind, allowing you to focus on expansion rather than expenses. Business credit line vs business loan: which financing option is right? If commitment and stability are what you need to thrive, a business loan could be the right pick.
Summarizing the Financing Faces
Alright, let’s wrap this up with some real talk. When it comes to the classic tussle of business credit line vs business loan: which financing option is right?, it boils down to your business DNA. Do you need funds that flow like water, adapting to the shape of your needs, much like a business credit line does? Or are you a strategy buff, craving the solid comfort of a business loan’s structure and reliability? Either way, it’s all about what fits your enterprise’s groove. So, take a deep breath, weigh your options, and let your business heart lead the way. In every decision lies an opportunity, and the right financing choice is just another step in crafting your business legacy.

